The demand spike hygiene companies enjoyed during the pandemic is over. A review of the latest five fiscal years shows the models that keep compounding — recurring services and solutions — pulling clearly ahead of product-volume businesses.
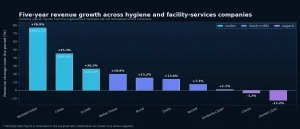
Between FY2021 and FY2025, the ten largest public-health and hygiene businesses in the US and Europe grew at sharply different speeds. The pattern is consistent: the three fastest growers all sell recurring outcomes — pest control, uniforms and facility hygiene, cleaning and sanitation solutions — rather than product volume.
The leaders
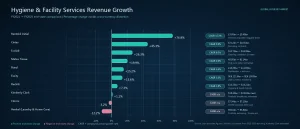
Rentokil Initial (UK) grew revenue from £3.05bn to £5.40bn (converted from the USD reporting it adopted in 2025), a +76.9% increase and a 15.3% CAGR. The Terminix acquisition in October 2022 was the single largest growth lever — one deal that remade the group’s scale in North America.
Cintas (US) compounded +45.3% (9.8% CAGR), from $7.12bn to $10.34bn, on contract renewals, cross-selling and add-on facility services.
Ecolab (US) grew +26.3% (6.0% CAGR), from $12.73bn to $16.08bn, across cleaning, sanitation, water-treatment and infection-prevention solutions.
The steady middle
Metsä Tissue (Finland) rose +19.9% (€0.95bn → €1.14bn); tissue prices spiked on pulp-cost inflation in 2022–23 before normalizing, yet the five-year end-state remains clearly higher. Bunzl (UK), the global distributor of cleaning and hygiene consumables, added +15.2% (£10.29bn → £11.85bn) on resilient distribution economics and serial bolt-on acquisitions. Essity (Sweden) grew +13.6% (SEK 121.9bn → SEK 138.5bn); its 2025 reported net sales eased 4.8% on currency, while organic growth stayed positive. Reckitt (UK), owner of Lysol, Dettol and Finish, gained +7.3% (£13.23bn → £14.21bn).
The laggards — often by design
Kimberly-Clark (US) ended the period roughly flat (+1.1%, estimated) — but deliberately: it is divesting the low-margin International Family of Products tissue-export business, with FY2025 continuing operations at $16.45bn. Clorox (US) is down -3.2%, still comparing against a COVID-elevated 2021 base. Henkel’s Laundry & Home Care division fell -12.2% — the sharpest drop — reflecting portfolio reshaping, including the exit of the Russian business.
Three patterns worth noting
- Services and contracts compound; product volume doesn’t.The three fastest growers sell recurring outcomes, not boxes — the difference compounds every quarter.
- M&A remains the fastest lever.Rentokil’s +76.9% is largely one acquisition; Bunzl’s steady climb is built on a decades-long string of bolt-ons.
- Shrinking top lines are often strategy, not weakness.Kimberly-Clark and Henkel are cutting low-margin and export lines to protect profitability and focus portfolios.
Brand by brand
Rentokil Initial — hygiene and pest-control services, UK. Revenue rose from £3.05bn in FY2021 to £5.40bn in FY2025 (converted from the USD reporting adopted in 2025) — a 76.9% increase and a 15.3% CAGR, with the Terminix acquisition as the single biggest driver.
Cintas — facility services and hygiene supplies, US. From $7.12bn to $10.34bn (+45.3%, 9.8% CAGR), compounding on recurring uniform-rental and facility-service contracts.
Ecolab — cleaning, sanitation and water-treatment solutions, US. From $12.73bn to $16.08bn (+26.3%, 6.0% CAGR).
Metsä Tissue — tissue and greaseproof papers, Finland. From €0.95bn to €1.14bn (+19.9%, 4.6% CAGR); a 2022–23 price spike on pulp-cost inflation later normalized, but the five-year end-state remains clearly higher.
Bunzl — cleaning and hygiene products distribution, UK. From £10.29bn to £11.85bn (+15.2%, 3.6% CAGR) on distribution resilience and serial bolt-on acquisitions.
Essity — professional and consumer hygiene, Sweden. From SEK 121.9bn to SEK 138.5bn (+13.6%, 3.3% CAGR); 2025 reported net sales eased 4.8% on currency while organic growth stayed positive.
Reckitt — hygiene and health consumer brands (Lysol, Dettol, Finish), UK. From £13.23bn to £14.21bn (+7.3%, 1.8% CAGR).
Kimberly-Clark — tissue and professional hygiene, US. Roughly flat at $19.44bn → $19.65bn (estimated, +1.1%) — deliberately, as it divests the low-margin International Family of Products tissue-export business.
Clorox — cleaning and disinfecting products, US. From $7.34bn to $7.10bn (-3.2%), still comparing against a COVID-elevated 2021 base.
Henkel (Laundry & Home Care) — laundry and home care division, Germany. From €6.61bn to €5.80bn (-12.2%), the sharpest decline, reflecting portfolio reshaping including the exit of the Russian business.
* Kimberly-Clark FY2025 total estimated (reported continuing operations $16.45bn + divested IFP segment); Rentokil FY2025 converted from reported USD $6.91bn after the switch to USD reporting.
A partner to watch
Several of the companies above have built deep partnerships with CDWK over the past few years. Rooted in China’s public hygiene industry for 23 years, CDWK integrates R&D, production and sales — and it is growing at an astonishing pace.
With five product series distinct in design, CDWK has established strategic partnerships with more than 5,000 overseas customers. Equally strong in product quality and service, the company is committed to delivering customized, one-stop solutions for every type of customer.